business
Asian shares mostly fall as renewed fighting hits US-Iran ceasefire hopes
Asian stock markets mostly declined on Tuesday as fresh fighting raised doubts over the stability of the US-Iran ceasefire, while US futures also slipped.
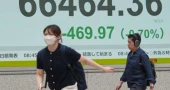
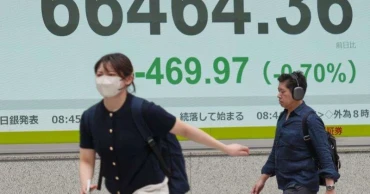
Japan’s benchmark Nikkei 225 fell 0.3% to close at 66,734.24, while South Korea’s Kospi dropped 0.2% to 8,772.08. Australia’s S&P/ASX 200 edged down less than 0.1% to 8,724.40.
In contrast, Hong Kong’s Hang Seng index rose 2.2% to 25,956.72 and China’s Shanghai Composite gained 0.4% to 4,075.34.
On Wall Street, US stocks had earlier reached new record highs on Monday. The S&P 500 rose 0.3% to 7,599.96, the Dow Jones Industrial Average gained 0.1% to 51,078.88, and the Nasdaq Composite climbed 0.4% to 27,086.81.
In bond markets, the yield on the 10-year US Treasury briefly climbed to 4.52% before easing to 4.46%.
Oil price movements continued to influence global markets. Airlines in the US came under pressure as fuel costs rose, with United Airlines shares falling 2.6% and Alaska Air Group down 3.3%.
In Asian trading, US crude oil fell 94 cents to $91.22 per barrel, while Brent crude dropped 90 cents to $94.08. Despite the decline, prices remain significantly higher than pre-conflict levels of around $70 per barrel.
Market analysts say much depends on whether Washington and Tehran can reach an agreement to reopen the Strait of Hormuz, a key route for global oil shipments from the Persian Gulf.
Analyst Stephen Innes said crude shortages have already forced refiners in Asia and Europe to cut production, warning that the impact is spreading across fuel supplies including petrol, diesel, jet fuel and other products.
The latest tensions follow ongoing military exchanges, with the United States saying it struck Iranian radar and drone facilities after an American drone was downed, while Iran claimed it targeted US forces in Kuwait—claims Washington says were intercepted.
In currency markets, the US dollar edged up to 159.72 Japanese yen, while the euro rose to $1.1654.
Meanwhile on Wall Street, Nvidia shares jumped 6.2% after new product announcements by CEO Jensen Huang, helping lift broader market sentiment.
4 months ago
Islami Bank customers continue demo demanding removal of new chairman
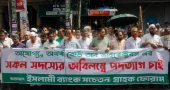
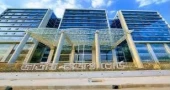
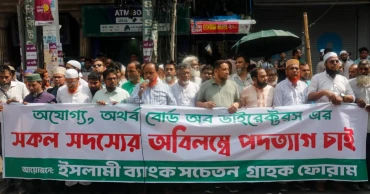
A section of Islami Bank customers continued demonstration in front of the bank headquarters at Dilkusha in Motijheel area for the second consecutive day on Tuesday, demanding the resignation of newly appointed chairman Khurshid Alam and all members of the bank’s board of directors.
The protesters under the banner of Islami Bank Conscious Customers Forum gathered in front of the bank’s headquarters around 9 am with placards.
They alleged irregularities in the recent changes in the bank’s top management and called for immediate withdrawal of the board including the chairman to ensure transparency and protect customer interests.
The demonstration continued till the filing of this report.
Police deployed water cannons, armoured vehicles, and extra personnel to maintain order.
The demonstrators accused Khurshid of having ties to the Chattogram-based S Alam Group and called for his immediate dismissal.
Police used water cannons, tear gas shells and sound grenades to disperse protesters outside Islami Bank head office on Monday, triggering a clash that left demonstrators and policemen injured.
4 months ago
Newly appointed Islami Bank Chairman will not be removed: Bangladesh Bank
Bangladesh Bank has confirmed that the newly appointed Chairman of Islami Bank Bangladesh PLC, Md. Khorshid Alam will not be removed from his post despite ongoing street protests demanding his resignation.
The announcement came on Monday from central bank spokesperson Arief Hossain Khan, following violent clashes outside the Islami Bank headquarters in Motijheel earlier in the day.
A group of demonstrators, rallying under the banner of the "Islami Bank Customers' Forum," staged a protest in front of the head office on Monday morning to demand the cancellation of Khorshid Alam’s appointment. The situation escalated when police used batons, water cannons, tear gas, and sound grenades to disperse the crowd.
Responding to the demonstrations, central bank spokesperson Arief Hossain Khan stated that the regulatory appointment has no connection to the street agitation.
"The movement has no link to the appointment. If Bangladesh Bank alters a decision today because of a protest, and then a counter-group launches an agitation opposing that new decision, what will the central bank do? Bangladesh Bank will move at its own pace based on its independent procedures. There is no possibility of changing the central bank’s decision due to street demonstrations," Khan told UNB.
Bangladesh Bank appointed Md. Khorshid Alam, a former deputy governor of the central bank, as the chairman of Islami Bank on the night of May 24.
The appointment followed the sudden resignation earlier that day of M Zubaidur Rahman, who had been appointed as chairman during the interim government's tenure. Rahman resigned after facing intense pressure and demonstrations from individuals identifying themselves as bank officials and customers. Sources added that the Managing Director (MD) of the bank is also currently on extended leave.
Meanwhile, Bangladesh Jamaat-e-Islami strongly condemned the police action against the demonstrating customers outside the bank's headquarters.
In a statement issued on Monday, Jamaat-e-Islami Secretary General Mia Golam Porwar said that ordinary account holders were conducting a peaceful sit-in program under the "Islami Bank Customers' Forum" banner when police initiated an unprovoked baton charge and used teargas and water cannons.
Denouncing the use of force, Porwar expressed his full solidarity with the customers, describing their demands as logical and just.
4 months ago
Remittance inflows grow by 15.3 percent in May; receipts $32.75b in FY26 so far
Bangladesh witnessed a massive surge in inward remittances with a staggering 15.34 percent growth in May 2026 compared to the corresponding period of last year, according to thelatest data from Bangladesh Bank.
Expatriate workers sent US$ 3.42 billion as remittance between May 1-31, up sharply from the $2.96 billion recorded during the same period in May 2025.
Central bank officials noted that the inflow spiked dramatically as expatriates sent additional funds to their relatives ahead of Eid-ul-Azha, a major religious festival celebrated on May 28.
With this latest monthly surge, total remittance inflows from July 2025 to May 2026 reached $32.75 billion, marking a robust 19 percent growth for the current fiscal year. During the corresponding period of the previous fiscal year (July 2024 to May 2025), the country received$27.5 billion.
Arief Hossain Khan, Executive Director and Spokesperson of Bangladesh Bank, told UNB that the central bank will continue its policy initiatives to keep this momentum alive. "The central bank willcontinue policy support to encourage remittance through legal channels," he said.
Financial analyst and Additional Research Director of the Centre for Policy Dialogue (CPD), Tawfiqul Islam Khan, attributed this significant momentum to a combination of policy and seasonal factors.
He told UNB that the growth was driven by the continuous streamlining of digital banking channels, robust seasonal flows ahead of the major festival, and competitive exchange rates offered by commercial banks.
The steady growth in the remittance architecture provides a major cushion for the country's foreign exchange reserves and offers critical support to macroeconomic stability amid global economicheadwinds.
4 months ago
Japan, South Korea stocks hit records as oil rises on Iran ceasefire doubts
Stock markets in Japan and South Korea climbed to record highs on Monday, driven by strong gains in technology shares and optimism over the global artificial intelligence boom, while uncertainty over the Iran war ceasefire kept oil prices elevated.
Oil prices rose more than 2% as investors closely watched ongoing U.S.-Iran talks, including discussions on reopening the Strait of Hormuz, a key route for global oil and gas shipments.
Asian markets broadly advanced, with Japan’s and South Korea’s benchmark indexes hitting new intraday records. The rally was led by technology stocks, as investors continued to bet on strong demand for AI-related industries.
Japan’s Nikkei 225 rose more than 1.3% and crossed the 67,000 level for the first time, reaching 67,231.28. Shares of SoftBank Group surged more than 9%, adding to recent record gains.
In South Korea, the Kospi index jumped nearly 5% to an all-time high of 8,874.16. Shares of Samsung Electronics rose more than 9%. Official data also showed South Korea’s exports surged 53% in May, supported by strong global demand for semiconductors.
Over the past month, Japan’s Nikkei has gained more than 12%, while South Korea’s Kospi has surged over 27%, reflecting strong momentum in regional equities.
Elsewhere in Asia, Hong Kong’s Hang Seng index rose 0.9%, while China’s Shanghai Composite slipped slightly after weaker-than-expected factory activity data signaled slowing export demand. Australia’s S&P/ASX 200 also edged lower, while Taiwan’s Taiex and India’s Sensex posted gains.
Market sentiment remains influenced by uncertainty over the future of the Iran conflict. Investors are watching whether a proposed ceasefire extension will hold, even as optimism around artificial intelligence and corporate earnings continues to support global equities, including on Wall Street.
Brent crude oil rose 2.4% to $93.33 per barrel in early trading, up sharply from about $70 in late February before the conflict began. U.S. crude also climbed 2.8% to $89.76 per barrel.
On Friday, Wall Street indexes closed at record levels, supported by strong gains in major technology stocks. The S&P 500, Dow Jones Industrial Average and Nasdaq Composite all posted fresh highs, led by companies tied to AI-driven demand.
In currency markets, the U.S. dollar strengthened against the Japanese yen, while the euro weakened slightly.
4 months ago
NBR warns jobseekers against fraud promising Income Tax Department jobs
The National Board of Revenue (NBR) on Monday warned jobseekers and their guardians against fraudsters who are collecting money by falsely promising jobs in the Income Tax Department.
In a press release, the revenue authority said it had received information that certain fraud rings in different parts of the country were attempting to deceive job applicants by claiming they could secure appointments in the Income Tax Department in exchange for money.
According to the NBR, the main objective of these fraudsters is to exploit candidates who would otherwise obtain jobs through the regular recruitment process on merit.
The revenue collecting agency said the fraudsters often mislead successful candidates into believing that their appointments were secured through financial transactions.
The NBR noted that while some candidates who fail to secure jobs due to a lack of qualifications may receive refunds from the fraudsters, those who are selected through their own merit are likely to lose the money paid to the criminal networks.
The revenue authority assured the public that the ongoing recruitment process for vacant posts in the Income Tax is being conducted with full transparency and accountability in accordance with legal procedures.
It said eligible candidates would be selected by a committee comprising representatives from the Ministry of Public Administration, the Internal Resources Division, the Bangladesh Public Service Commission and the Income Tax Department.
It also requested people to report any information regarding individuals or groups collecting money in the name of securing jobs in the Income Tax to the relevant Tax Commissioner’s Office or the NBR’s Public Relations Officer.
The authority reiterated that no payment is required to obtain employment in the department and stressed that appointments would be made solely on the basis of merit and through the prescribed recruitment procedures.
4 months ago
Closed sugar mill costs Tk 24 lakh a month, revival uncertain
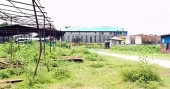
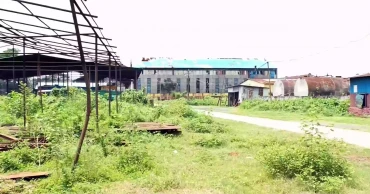
Once a vibrant industrial hub supporting thousands of families in northern Bangladesh, Shyampur Sugar Mills in Rangpur now stands largely silent, its machinery rusting away while the government continues to spend nearly Tk 24 lakh every month despite production remaining suspended since 2020.
The state-owned mill, one of the oldest heavy industries in the region, was shut down during the 2020-21 crushing season following years of mounting losses and declining sugarcane production.
Although the interim government announced plans to revive closed sugar mills and lifted the suspension order in late 2024, local residents, workers and farmers say little visible progress has been made on restarting operations.
Now uncertainty continues to loom over thousands of sugarcane growers, workers and businesses that once depended on the mill for their livelihoods.
Bangladesh Sugar and Food Industries Corporation (BSFIC), a taskforce formed by the interim government, recommended reopening several closed mills including Shyampur Sugar Mills in Rangpur and Setabganj Sugar Mill in Dinajpur.
Based on the taskforce recommendations, BSFIC withdrew the suspension order on December 15, 2024, and proposed phased government financial assistance over three years to resume sugarcane crushing from the 2027-28 season.
However, the revival plan hit a major hurdle when the Finance Division declined a proposal seeking Tk 51.70 crore for Shyampur Sugar Mills during the 2024-25 and 2025-26 fiscal years.
In a response to the Industries Ministry, the Finance Division noted that BSFIC has already received substantial operational loans from the government over the past two decades and described the corporation as a loss-making entity. It also pointed out that the mills had originally been closed to reduce the government’s subsidy burden.
Silent Factory, Continuing Costs
Despite the suspension of production, the mill still employs 63 personnel, including permanent and temporary staff responsible for administration, security and maintenance.
Mill Assistant Manager (Store) Debashish Singha Roy said approximately Tk 24 lakh is spent every month on salaries and allowances.
“Although monthly expenditure is around Tk 24 lakh the mill earns only about Tk 6-7 lakh annually by leasing out some of its land. We still need manpower to protect and maintain the land, machinery, residential quarters and administrative buildings. Otherwise, whatever remains of the mill’s assets may not survive,” he said.
Workers said the closure has transformed what was once a bustling industrial complex into a deserted facility.
“Shyampur Sugar Mill was the economic heartbeat of this area. Thousands of families depended on it,” said Abu Sufian, former general secretary of the Sugar Mill Employees’ Union.
“After the closure, many temporary workers lost their jobs. When the interim government announced plans to restart the mill, people became hopeful. But nearly a year and a half later, no visible initiative has been taken. This is increasing frustration among workers and employees,” he added.
He urged the government to allocate funds in the upcoming budget for modernising and reopening the mill.
Once a Symbol of Industrial Growth
Established in 1964 at Shyampur Bazar in Badarganj upazila, the mill formally began operations in 1967 on 111.45 acres of land.
Designed to crush 1,016 tonnes of sugarcane daily, it had an annual production capacity of 10,161 tonnes of sugar.
Ki For decades, it played a key role in the agricultural economy of Rangpur and surrounding districts.
Although profitable during its early years, the mill started incurring losses after 2000.
Rising bank liabilities, interest payments, employee provident fund obligations and operational inefficiencies reportedly pushed accumulated losses into several hundred crore taka.
A government committee comprising representatives from the industries, commerce, finance and agriculture ministries eventually recommended suspending crushing operations, leading to the mill’s closure in the 2020-21 season.
Management attributed the losses to declining sugarcane cultivation and outdated machinery.
However, workers and farmers disputed that explanation, blaming corruption, mismanagement and inefficient staffing for the deteriorating financial condition.
Impact on Farmers and Local Economy
The closure has significantly affected local sugarcane cultivation.
Fazlul Haque, a farmer from Badarganj, said he stopped growing sugarcane after the mill was shut down.
“While the mill was operating, I cultivated sugarcane regularly. Now I grow paddy, wheat, maize and vegetables instead,” he said.
According to BSFIC officials, around 300 acres of sugarcane have been cultivated this year under the Joypurhat Sugar Mill sub-zone. The harvested cane is being transported to Joypurhat for processing.
BSFIC Assistant Manager (Extension) Zahidul Islam, who oversees Shyampur operations, said reopening the mill would require sustained preparation.
“A sugar mill cannot be run with sugarcane from just one season. Even if funds are allocated this year, it will take at least three crushing seasons to fully restore sugar production operations,” he said.
Local businessman Manik Mia said the closure has weakened the area’s economy.
“Shyampur Sugar Mill was one of the major industrial establishments in this agricultural region. Several thousand families were directly or indirectly connected to it. Many people are now struggling after losing their livelihoods,” he said.
However, the current government has also given assurances over re-opening closed sugar mills.
Industries and Commerce Minister Khandakar Abdul Muktadir has said the current government is determined to reopen the closed state-owned sugar mills.
“But in this (reopening) process, decisions will be made with utmost importance to the factors – the interests of sugarcane farmers and workers, and the long-term profitable operation of the mills,” he said at a view-exchange meeting with sugarcane farmers, arranged by Panchagarh Sugar Mills Limited in Panchagarh recently .
4 months ago
Govt eyes leather sector overhaul, vows long-term export push
The government aims to transform Bangladesh's leather industry into a stronger, export-oriented sector by ensuring maximum utilisation of sacrificial animal hides from Eid-ul-Azha, Commerce Minister Khandakar Abdul Muktadir said on Friday.
Speaking to reporters after inspecting raw hide trading operations at Posta in Lalbagh, the minister said a comprehensive, long-term plan covering development, preservation, processing and export capacity of the leather sector would be placed before the nation by July.
“We believe that through the government's coordinated efforts, active participation of traders and depot owners, and mosque- and madrasa-based hide preservation drives, most of the sacrificial hides this year will be collected in usable condition,” he said.
The minister, who visited Aminbazar on Thursday and Posta and Hemayetpur in Savar on Friday, noted that large volumes of hides had already reached traders and salting was underway. “The full processing cycle normally takes two to three months as hides do not all arrive in Dhaka simultaneously.”
Muktadir stressed the importance of timely salting, warning that hides left untreated for more than four to six hours, especially at temperatures of 38 to 40 degrees Celsius, risk rapid deterioration. Properly salted hides, he said, can be preserved for three to four months.
He outlined the leather production chain from raw hide to wet blue, crust leather and finally finished leather, used to manufacture shoes, sandals, belts and other goods, underscoring why preservation quality directly determines industrial value.
On concerns over hide smuggling, the minister said the relevant authorities had been directed to maintain strict surveillance. “We do not want a single hide to be smuggled out of the country.”
Regarding the Savar leather industrial estate and its Central Effluent Treatment Plant (CETP), Muktadir acknowledged operational shortfalls. The CETP has a project capacity of 25,000 cubic metres per day but is currently functioning at only 14,000 to 18,000 cubic metres. “Reforms would be undertaken to address the gap and attract further investment.”
The minister also called for modernising and mechanising the slaughtering and skinning process to improve hide quality, noting that improper skinning significantly degrades the raw material.
He said Bangladesh's leather and leather goods market including exports is currently valued at approximately Tk 12,000 to 15,000 crore, with a substantial domestic market alongside. “The government has already distributed free salt through BSCIC and district administrations to madrasas and collection centres to ensure proper hide preservation.”
Industry Secretary Md Obaidur Rahman, Commerce Secretary (routine duty) Md Abdur Rahim Khan, BSCIC Director General Md Saiful Islam and leaders of the Bangladesh Tanners Association were present on the occasion.
4 months ago
Govt giving highest priority to proper management of rawhides: Minister
Industries, Commerce, and Textiles and Jute Minister Khandaker Abdul Muqtadir on Thursday said the government is giving the highest priority to ensuring proper management of sacrificial animal hides during the Eid-ul-Azha season.
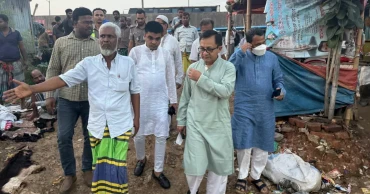
He made the remarks while visiting the leather trading centre at Amin Bazar in Dhaka to inspect the collection, preservation and marketing activities of sacrificial hides.
During the inspection, the minister spoke with rawhide buyers, sellers, warehouse owners and traders and enquired about market conditions, prices, preservation facilities and overall management activities.
“The government is working with utmost importance to ensure smooth management of sacrificial hides during the Eid season,” the minister said.
Describing the leather industry as an important sector of the country’s economy, he urged all stakeholders concerned to perform their responsibilities sincerely.
The minister also said the government remains alert to prevent any irregularities, syndicates or wastage of hides and that regular monitoring activities at the field level would continue.
Commerce Ministry Secretary (Routine Duty) Md Abdur Rahim Khan was present during the visit.
4 months ago
Asian markets fall, oil prices rise after fresh US strikes on Iran
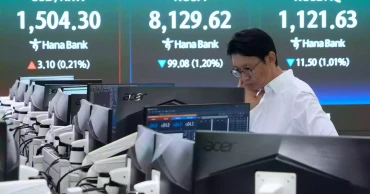
Asian stock markets fell on Thursday as tensions rose following fresh US military strikes on Iran, which Washington described as defensive actions.
At the same time, oil prices climbed by more than $2 per barrel after dropping sharply in the previous session, while US futures also edged lower.
US officials said Central Command forces shot down four Iranian attack drones near the Strait of Hormuz. They also struck a drone control facility in Bandar Abbas that was preparing to launch another drone. These strikes came after earlier military actions earlier in the week.
US President Donald Trump said Iran is “negotiating on fumes” and insisted that upcoming US elections would not influence his approach to ending the ongoing conflict, now in its third month.
Asian markets under pressure
In early trading, Japan’s Nikkei 225 fell 0.4%, while South Korea’s Kospi also dropped 0.4%.
Hong Kong’s Hang Seng Index declined 1.4%, and China’s Shanghai Composite edged up slightly by 0.1%.
Australia’s S&P/ASX 200 slipped 1.4%, while Taiwan’s main index also recorded losses.
Analysts said uncertainty around US–Iran negotiations and the fragile ceasefire continued to weigh on investor confidence.
“Markets remain cautious as it is still unclear whether a lasting deal can be reached,” said Tan Boon Heng of Mizuho Bank.
He added that while both sides appear to avoid escalating tensions publicly, major disagreements remain unresolved.
Oil prices rebound
Oil prices, which had dropped sharply earlier in the week, rose again on renewed concerns over supply risks in the Middle East.
Brent crude gained more than $2 to around $94 per barrel in early trading, while US crude also moved higher.
Earlier, oil had fallen after hopes that a ceasefire between the US and Iran might hold, easing fears over disruptions in the Strait of Hormuz — a key global oil shipping route.
Wall Street at record highs
On Wednesday, US stock markets had closed slightly higher, with all three major indexes — the S&P 500, Dow Jones Industrial Average, and Nasdaq — reaching record levels.
Shares of airlines and cruise companies rose as falling oil prices earlier in the week boosted expectations of lower fuel costs.
Despite ongoing geopolitical uncertainty and inflation concerns, strong corporate earnings have helped support market gains.
Currency movements
In currency trading, the US dollar held steady against the Japanese yen, while the euro slipped slightly.
5 months ago