Global stock markets mostly advanced on Wednesday after Democrats secured majorities in both chambers of the US Congress in the midterm elections, while US stock futures edged higher and oil prices retreated.
Futures for the S&P 500 gained 0.2%, while those linked to the Dow Jones Industrial Average rose 0.4%.
The election results marked a significant setback for Republican leadership and are expected to usher in a period of stronger congressional opposition to US President Donald Trump.
Financial markets generally favour a divided government, with control shared between Republicans and Democrats, as it reduces the likelihood of major policy shifts that could disrupt the economy.
Stephen Brown of Capital Economics said the Democrats' gains were unlikely to significantly alter the near-term policy outlook, as the party still lacked a filibuster-proof Senate majority and Trump retained the power to veto legislation.
Investors have recently focused on developments in artificial intelligence (AI), with technology stocks experiencing periods of selling amid concerns that their valuations have risen too high.
European markets advance
In early European trading, France's CAC 40 gained 0.4% to 8,055.02, Britain's FTSE 100 edged up 0.1% to 10,646.43, and Germany's DAX advanced 0.5% to 25,995.13.
Investors were awaiting the eurozone's preliminary October consumer price inflation figures due Wednesday, while the Bank of England's interest rate decision scheduled for Thursday also remained in focus.
Mixed performance across Asian markets
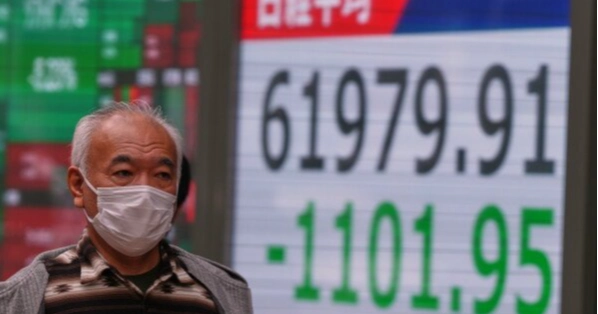
Asian markets delivered mixed performances, with Japan's Nikkei 225 falling 1.4% to 62,188.63.
Shares of SoftBank Group, an investor in OpenAI, declined 3.2%, while memory chipmaker Kioxia Holdings dropped 5.4% after its October-December business outlook fell short of market expectations.
South Korea's Kospi gained 0.6% to 5,683.80, despite SK Hynix slipping 0.1% and Samsung Electronics declining 0.7%.
Hong Kong's Hang Seng Index climbed 1.5% to 23,888.46, while the Shanghai Composite rose 2.2% to 3,686.17, recovering from its lowest level of the year recorded on Tuesday.
Australia's S&P/ASX 200 declined 0.6% to 8,834.50 following the central bank's interest rate hike on Tuesday. Taiwan's Taiex lost 0.8%, while India's Sensex advanced 0.3%.
Wall Street posts mixed results
On Tuesday, the S&P 500 gained 0.4%, although most of its constituent stocks ended lower. The Dow Jones Industrial Average fell 197 points, or 0.4%, while the Nasdaq Composite advanced 0.8%.
Chipmakers Nvidia and Broadcom provided the strongest support to the S&P 500. Shares of Microsoft, Amazon and Meta Platforms also rose more than 2%, partly reflecting investor interest in companies investing heavily in AI.
Apple, which has traditionally been viewed as less dependent on AI than other major technology companies, is also facing the impact of the AI boom.
Growing demand for memory chips from AI data centres has pushed up prices, increasing costs for Apple. The company expects lower profit margins for every dollar of revenue during the final three months of the year.
Several companies also gained after reporting better-than-expected summer-quarter earnings. DuPont surged 8.6%, recording one of the S&P 500's biggest gains, while Celanese advanced 5%.
Corporate earnings are expected to remain strong as the US economy continues to expand despite persistent inflation and elevated interest rates.
A positive US employment report released Tuesday showed that employers advertised more job vacancies at the end of September than economists had anticipated.
Following the report, the yield on the 10-year US Treasury rose to 4.96% from 4.91% late Monday.
Oil prices and currencies
In other trading on Wednesday, Brent crude, the international benchmark, rose 0.4% to $103.88 a barrel, while US benchmark crude gained 0.3% to $96.34 per barrel.
The US dollar weakened to 158.17 Japanese yen from 158.69 yen, while the euro strengthened to $1.1242 from $1.1194.